SIGNAL ORIGIN
Reported by: Holden Walter-Warner
Publication: The Real Deal
Original headline: 350 Park’s $3.3B loan underscores office trophy market’s financing strength / Vornado, Citadel’s 350 Park lands $3.3B financing
Date: August 5–8, 2026
STORY
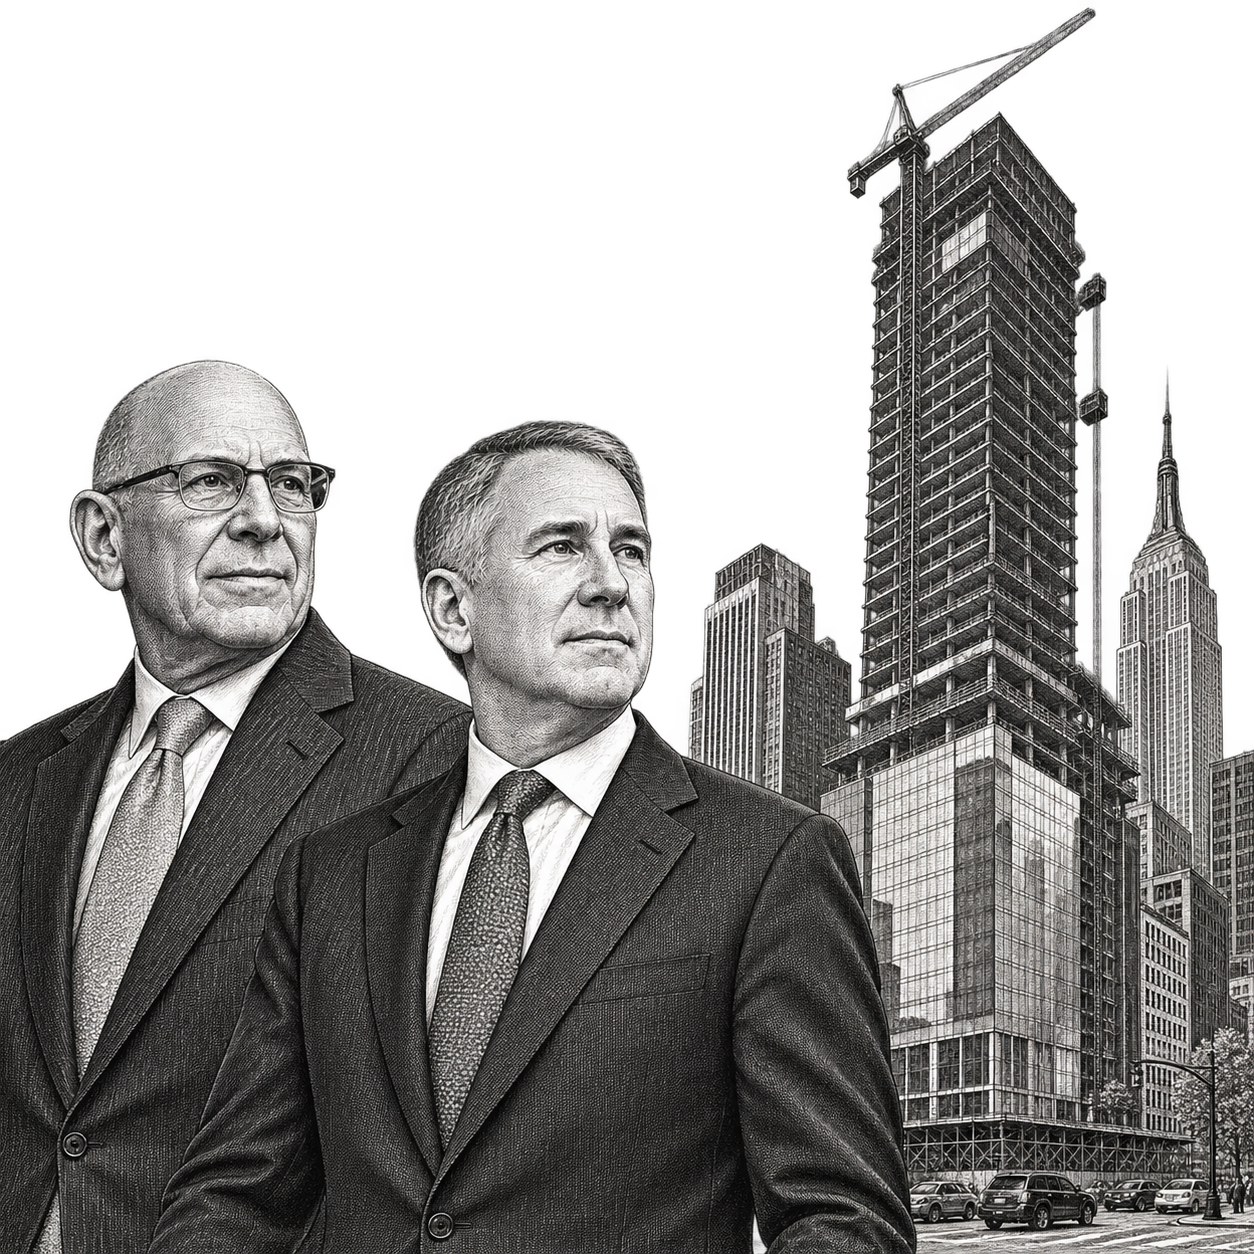
Vornado Realty Trust, Citadel and Rudin have secured a $3.3 billion construction loan for the 2 million-square-foot office tower at 350 Park Avenue in Manhattan. The financing covers roughly half the project’s estimated $6 billion cost and ranks among the largest construction loans in New York City history. Citadel will hold a 60 percent interest and anchor approximately 1 million square feet; Vornado is exercising its option for a 36 percent stake (valued at roughly $900 million for its land and building contribution); Rudin retains 4 percent. The partners are also considering a sale of a further 25 percent interest to an outside investor. Demolition is underway. The lender was not disclosed.
SIGNAL
Institutional capital is financing a landmark trophy office development in Midtown Manhattan through a record-scale construction loan secured by a high-quality tenant-anchored joint venture.
CAPITAL ANGLE
Sophisticated capital is demonstrating extreme selectivity in New York office construction finance. Lenders are prepared to underwrite multi-billion-dollar debt only when three non-replicable conditions converge: a prime Park Avenue site, a deep-pocketed, long-term corporate anchor occupying half the building, and experienced owners willing to retain substantial equity. The $3.3 billion loan at roughly 55 percent of total project cost signals that credit is available at scale for the absolute top tier, while the simultaneous consideration of a 25 percent equity sale indicates residual demand from institutional buyers for ownership exposure once construction risk is mitigated by tenancy. Capital is not returning to office broadly; it is concentrating exclusively in irreplaceable assets where tenant credit and location compress residual risk to levels acceptable for large-balance construction financing.
WHAT WE’RE WATCHING
- Potential sale of the remaining ~25 percent equity stake to an outside institutional investor
- Final lender identification and any subsequent syndication or permanent take-out financing
- Additional large-block pre-leasing commitments that could further de-risk or expand the capital structure